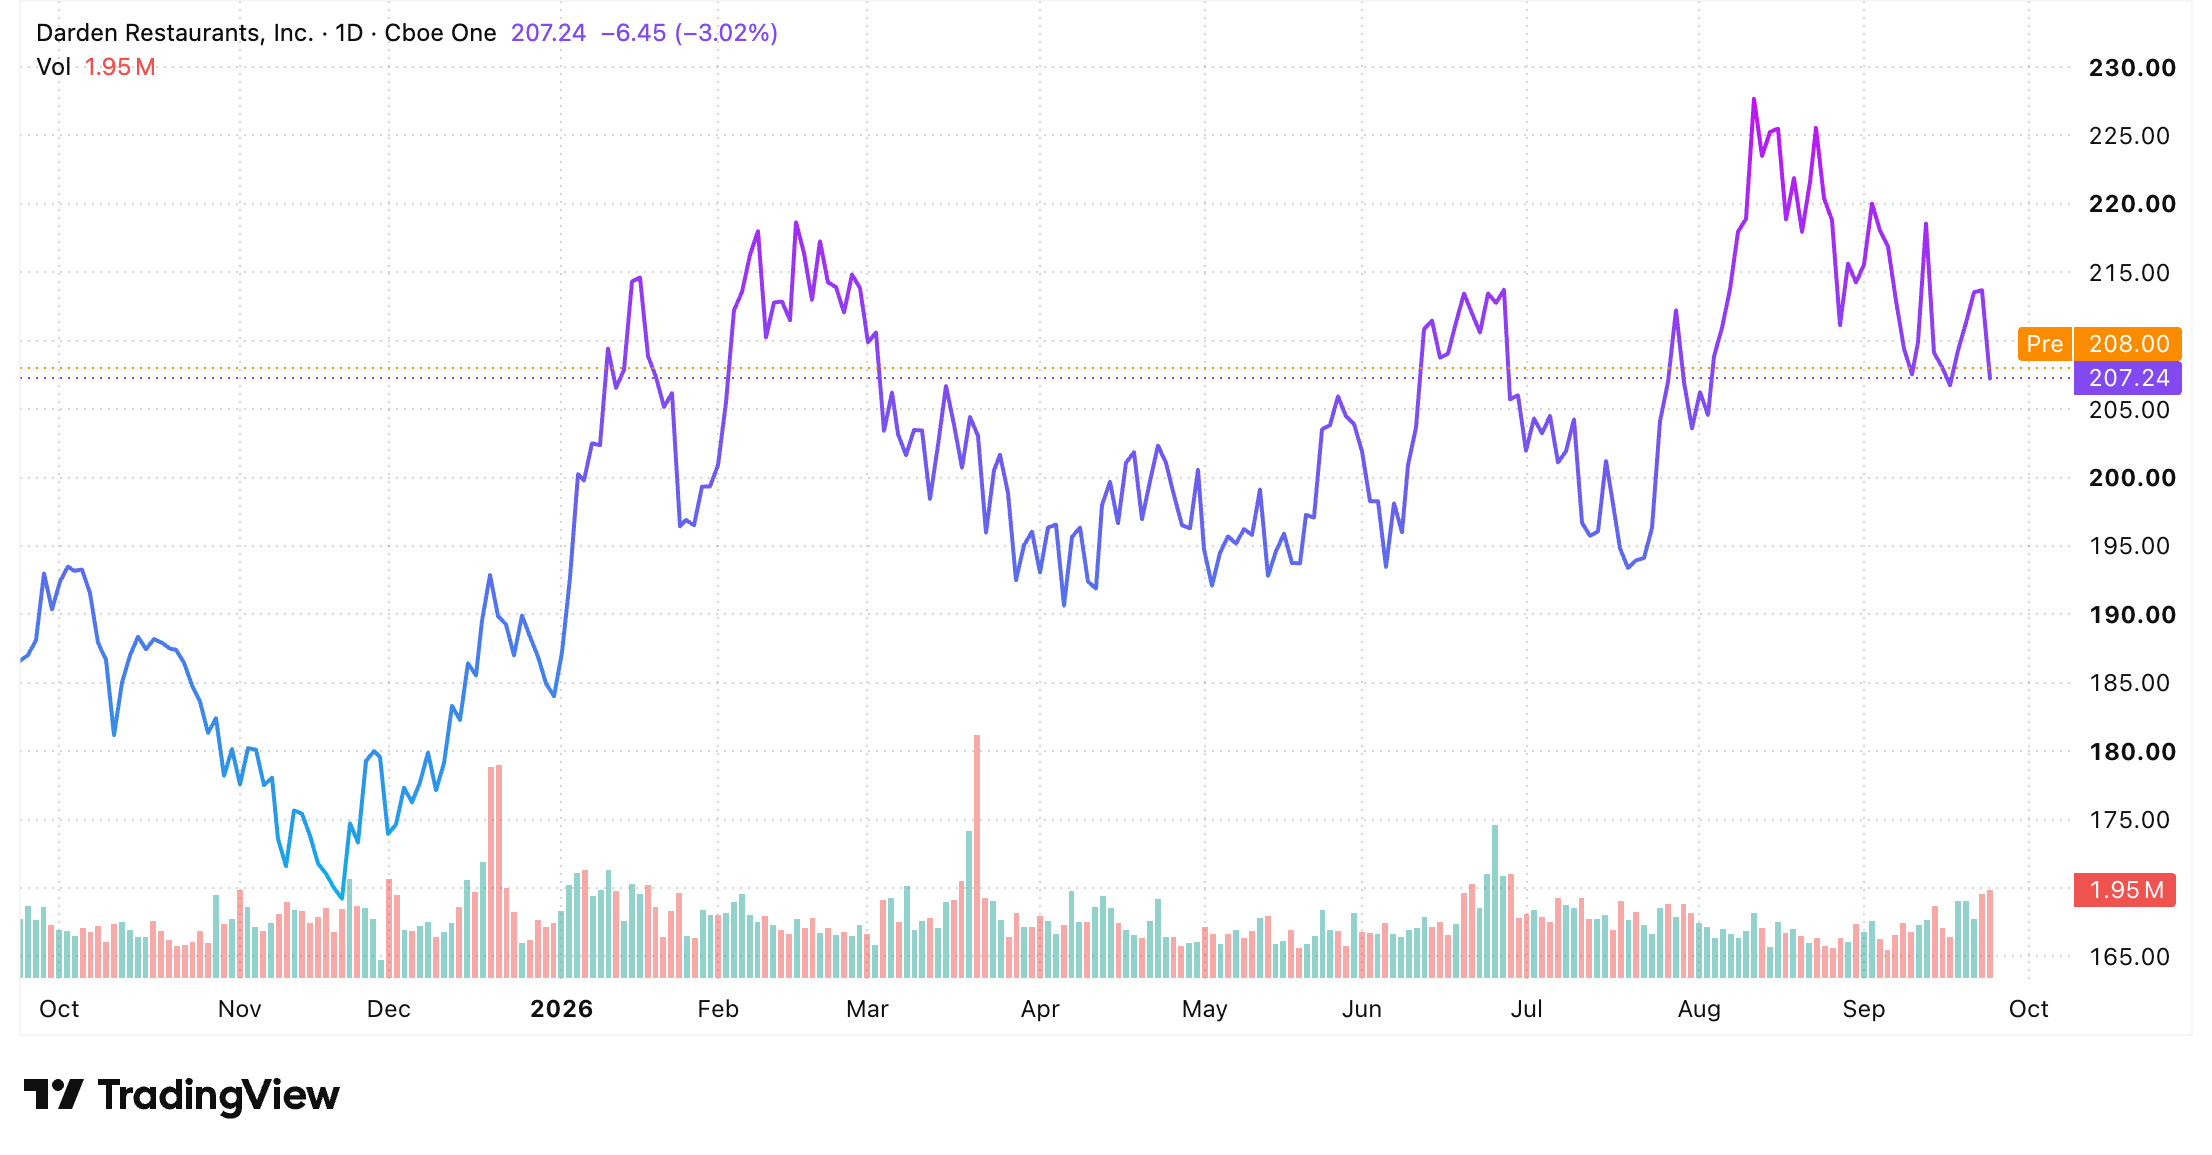
Darden matched its earnings estimate to the penny and dropped as much as 5% before the open. One line did it — and it says more about your neighbors' wallets than about pasta.
KEY POINTS
Olive Garden same-restaurant sales rose 1.1%. LongHorn rose 6.2%.
Adjusted earnings came in at $2.05, against $2.06 expected.
Operating margin fell to 10% from 11.1% — where your dividend comes from.
Costs rose 6.5% against sales up 5.1% — the same beef you're buying.
Full-year guidance reaffirmed, not raised: $11.10 to $11.35 a share
Blended same-restaurant sales rose 3.2%, against an industry running at 2.4%. Darden took share. And the stock fell anyway, because a company that beats its industry by eight-tenths of a point while its largest brand grows at half that rate has a problem the headline number hides.
Costs outran sales. That's beef and labor.
The same beef and labor you're paying for at the grocery store.
A year of gains, and yesterday's single-line reaction
Value Is The Weak Brand
Olive Garden is the cheap one. It's also the slow one.
Management named real reasons — the World Cup pulled eight-tenths of a point out of the quarter, and food-safety worries weighed early. Fair enough. But the gap between these two brands has persisted for four quarters now, and a World Cup does not last four quarters.
The likelier reading is the one Monday's issue raised: the households still spending are a narrower and wealthier slice than the surveys you answer capture, which is a different economy than the one in the headlines.
Which tells you something about who's still at the table near you. And who stopped coming.
Both Sides In Numbers
The bull case is that Darden still wins. Every segment posted positive growth, the company beat its industry again, and management reaffirmed full-year earnings of $11.10 to $11.35. The stock is up 12.9% this year and sits near a 52-week high of $227.68, which is most of what you'd have wanted from it. Solid, not spectacular.
The bear case lives in the margins. Operating margin fell to 10% from 11.1%. Down a point. Free cash flow margin dropped to 3.2% from 5.5% — more than a third of it gone in a year, while costs rose 6.5% against sales up 5.1%.
And reaffirming guidance rather than raising it is its own message. Wall Street expected a raise. It got a hold, and so did your holding.
For Band 3 holders, that margin line matters more to you than the comp. Profit you can spend comes out of margin, not out of traffic.
What To Watch From Here
Three numbers for you. Not the comp.
Whether Olive Garden reaccelerates without discounting. Whether beef costs ease. And whether free cash flow margin recovers from 3.2%.
For Band 1 holders, a share-gainer near its high on a reaffirmed guide is your patience question. For Band 3, the dividend is the reason to own it, and the dividend is paid from margin.
But Darden met every number. Your money still moved.
What to Watch
Two dates. Carnival is expected to report Tuesday, September 29 — another read on discretionary spending, from a customer base that overlaps with a steakhouse more than with a pasta chain. September CPI lands October 14, and the beef line in it is the same cost pressure Darden just showed you.
But the risk cutting the other way: management said September is trending better and beef costs should improve later in the year. If both hold, the margin line recovers and this quarter reads as noise.