The medical care ratio is the share of premiums spent on care. It decides whether the stock recovers — and it’s the same number inside your plan. Enrollment opens Thursday.
KEY POINTS
Consensus wants $4.12 a share, up from $2.92 — a 41% jump you’re paying for.
The medical care ratio, the share of your premium spent on care, is forecast at 90.1%.
Revenue is expected to fall 1.6%. The company is shrinking, not growing.
Shares sit about 18% below their July high, with no analyst rating it a sell.
UnitedHealth spent 86.7 cents of every premium dollar on care last quarter. Down from 89.4 cents a year earlier.
That improvement is why the stock recovered. It’s also, by definition, a smaller share of premiums going to care.
The company reports this morning. Medicare’s annual enrollment window opens Thursday, two days later, for you.
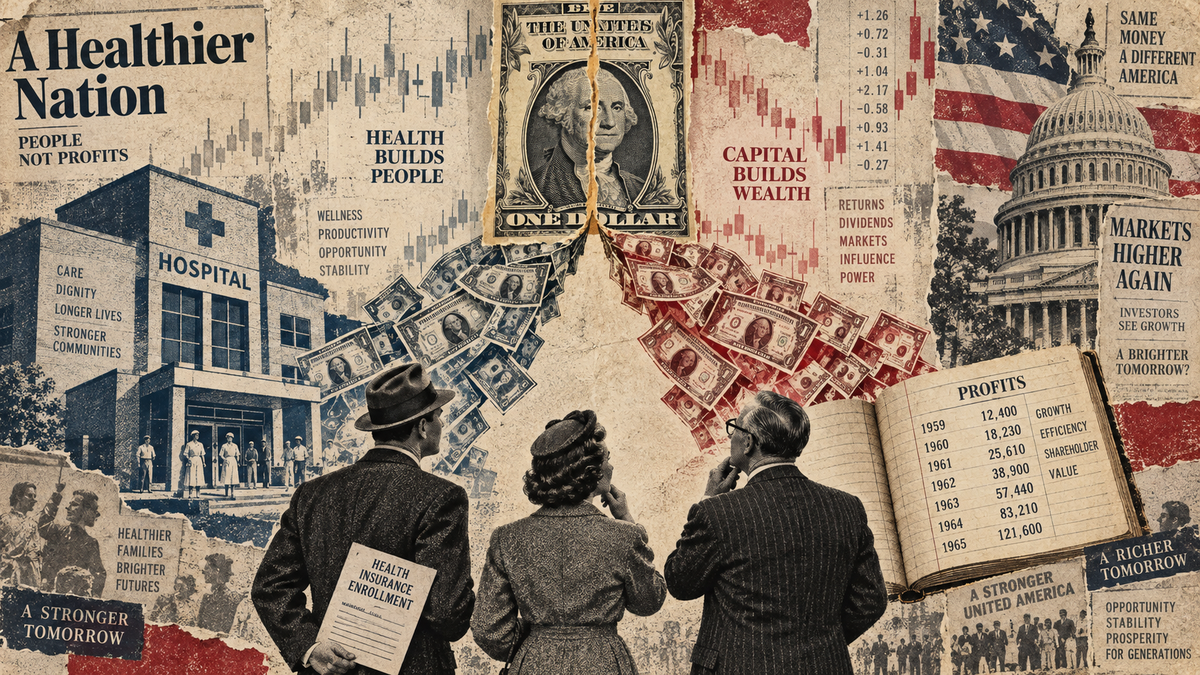
Same number. Two sides of your household. And you may be on both of them.
Where UnitedHealth Stands Today
What you’re buying into this morning:
•
Consensus adjusted earnings about $4.12 a share, against $2.92 a year ago
•
Revenue expected near $111.3 billion, down roughly 1.6%
Full-year guidance $19.50 to $20.00 adjusted, raised in July
•
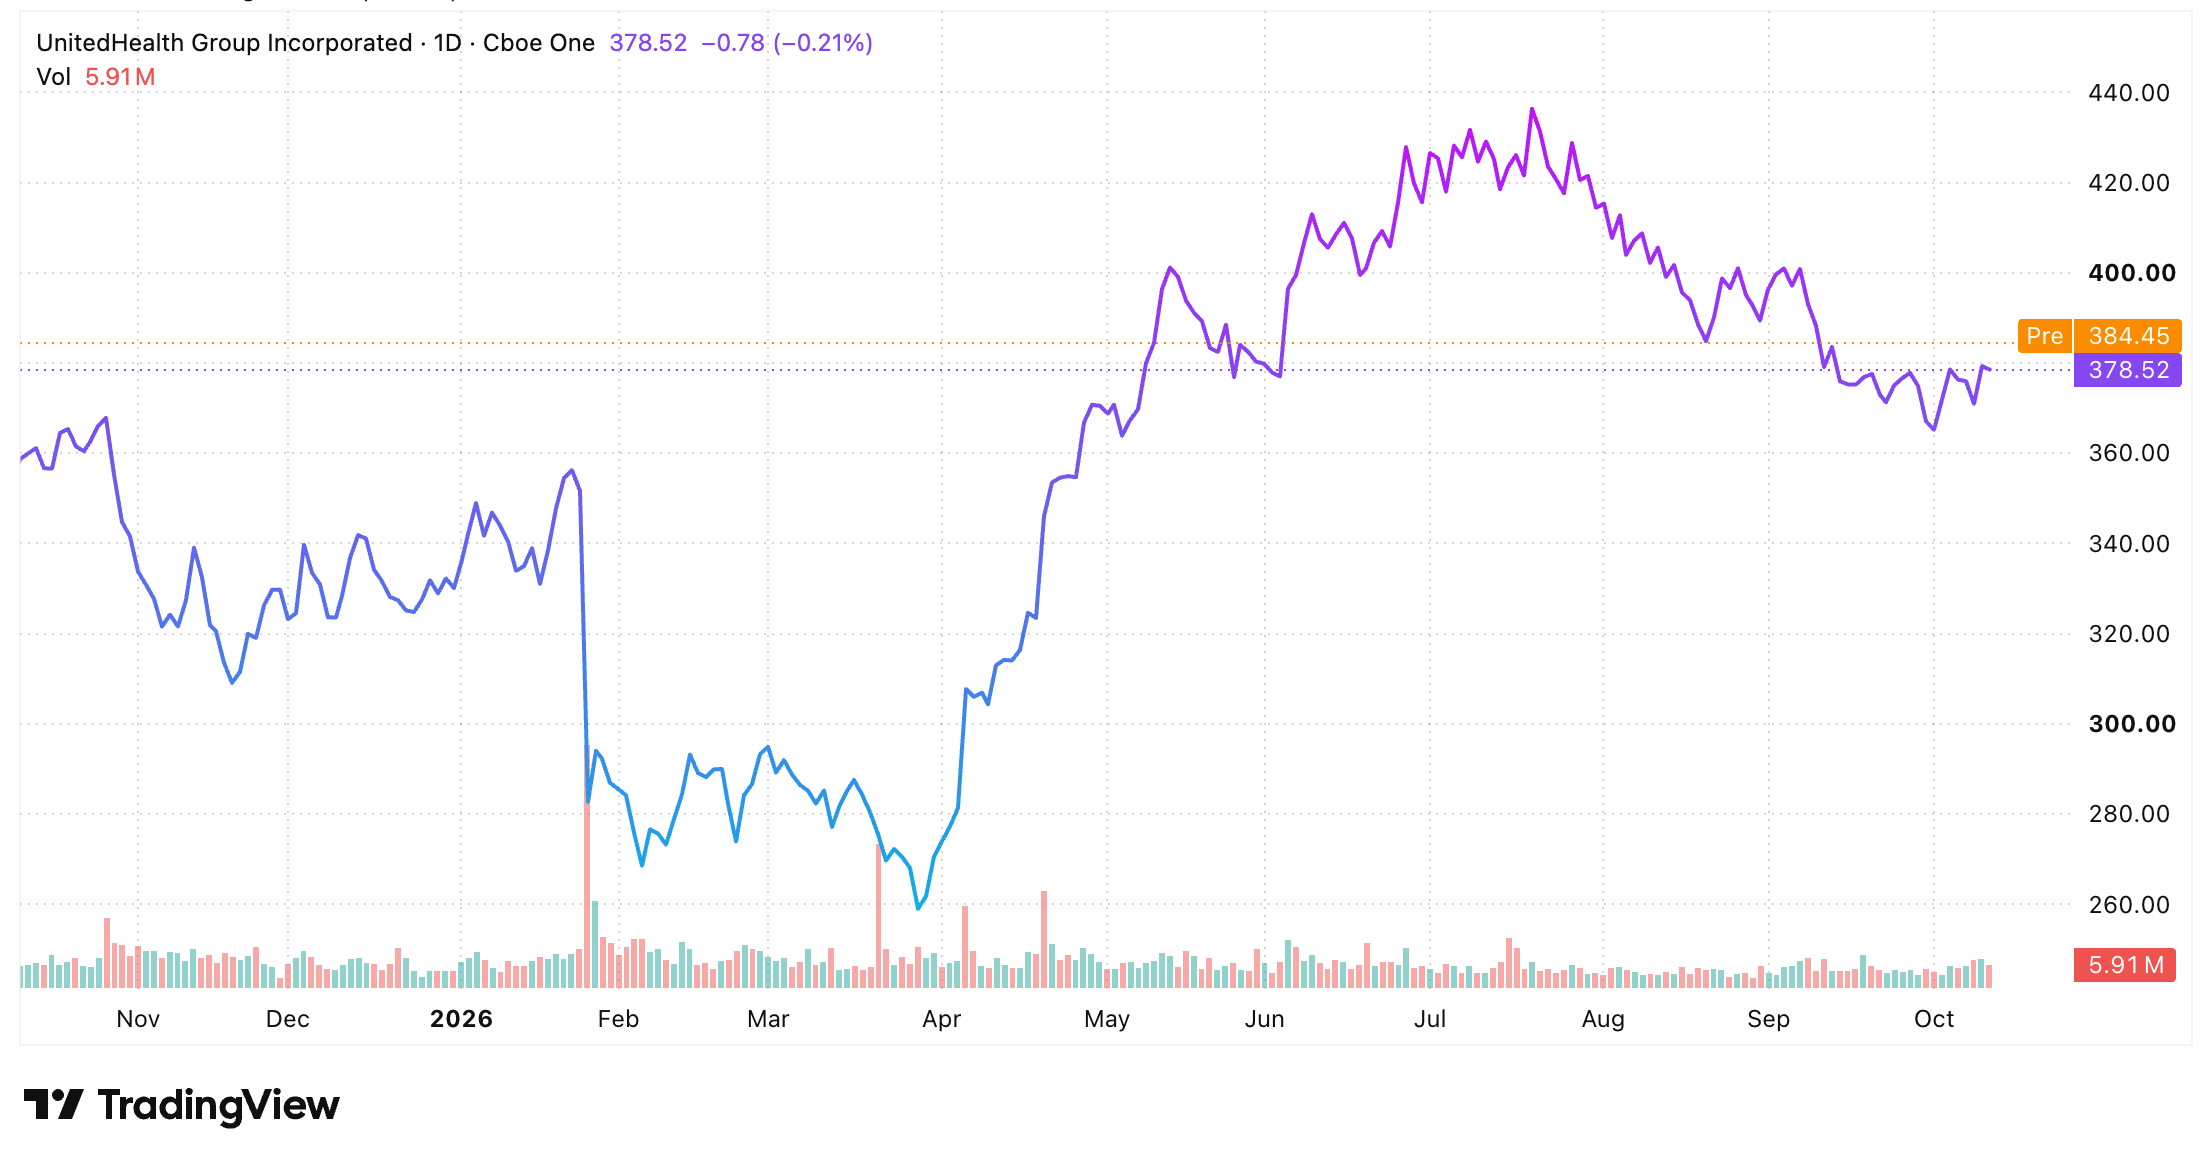
Shares about 18% below their July high, near $379
Earnings up 41% on revenue down 1.6%. That gap is the whole company right now — UnitedHealth isn’t growing, it’s repairing, and the repair runs entirely through what it spends on care.
Analysts carry 17 Buys against four Holds, with an average target of $485. Not one sell.
And if your coverage comes through a Medicare Advantage plan, you’re inside that ratio rather than just invested in it.
Four quarters, four very different earnings reactions
What Could Break The Recovery
Start with the ratio that decides your return. Analysts expect 90.1% this quarter, against 89.9% a year ago.
Up, not down.
Full-year guidance assumes 88.1%. A third-quarter print above 90% does not kill that by itself — costs run seasonally — but it leaves little room. And the company has already told you it expects more earnings in the third quarter than the fourth.
Revenue is also shrinking. About 1.6% lower than last year, and roughly flat for the full year, because UnitedHealth has been exiting businesses and plans rather than winning new ones. Cost control has a floor. Exits run out.
And the stock has history here. It fell more than 14% after January’s report and rose 10.5% after April’s — the same company, two quarters apart, and your position sat through both.
Management raised full-year guidance on the back of it, to $19.50 to $20.00 adjusted, which is the number your position actually tracks.
And the capital return tells you more than the forecast does. UnitedHealth doubled its buyback plan to at least $5 billion from $2.5 billion, and lifted the dividend to $9.28 a share annualized, which is money committed rather than money forecast. Doubled it. Companies with a cost problem they can’t see the end of don’t double buybacks in the middle of it.
Cash from operations is guided near $24 billion, which funds the dividend you receive.
Piper Sandler called the 2027 Medicare star ratings resilient and said it would be a buyer into this report.
For Band 3 holders, that dividend is the part that reaches you.
Where The Numbers Actually Land
But one ratio settles this. Not earnings.
If the medical care ratio comes in near 90.1% and guidance holds, the repair is on schedule. Above it, with any softening of the full-year range, and January’s reaction is the template.
For Band 3 holders, there’s a second ledger — the same ratio that lifts the stock is the share of your premium going to care, and enrollment opens Thursday.
You can hold both positions at once. Most readers already do.
What to Watch
Two dates. Medicare’s annual enrollment window opens Thursday, October 15 and runs to December 7 — the one window where your plan choice is yours to change. And the Fed decides October 27 and 28, which matters here because a health insurer’s investment portfolio earns more at 5%.
The risk cutting against the bull case: guidance. Twice this year the quarter was fine and the outlook moved the stock double digits. Watch the 2027 commentary more than the 2026 number, because that’s the year your plan renews into.